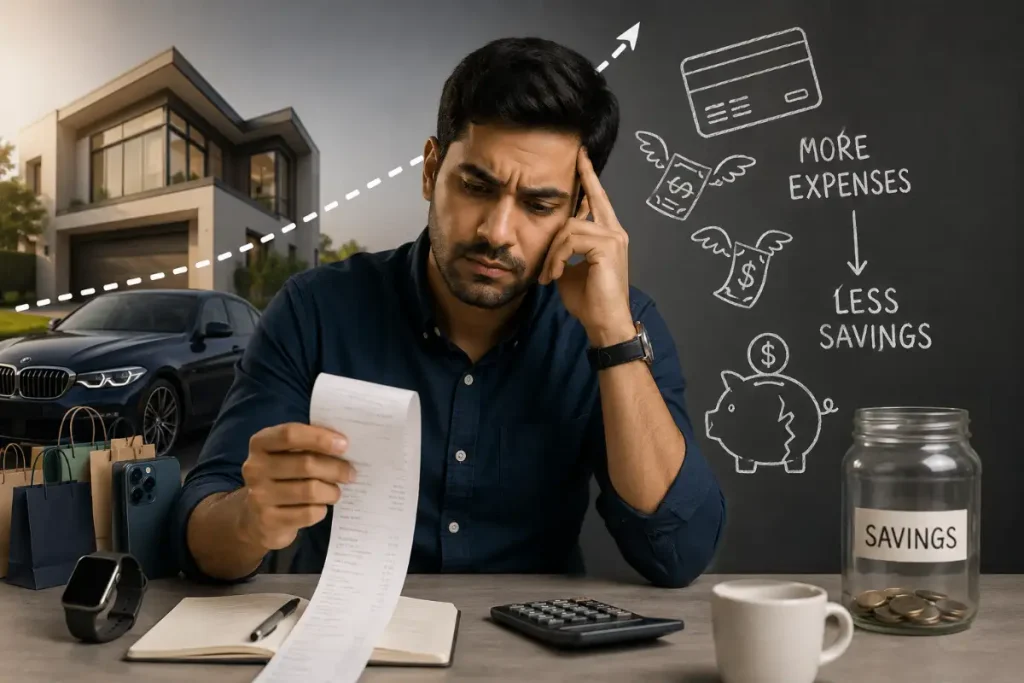
Most of us have a simple dream. We want to reach a point where we earn enough money to live comfortably. We want to stop worrying about the rent, cover our bills easily, and have a little left over for fun. But something strange happens when that goal finally arrives. As your income grows, your spending habits often start to climb right along with it.
This is what experts call lifestyle creep. It is the sneaky process where your “wants” slowly become your “needs.” You get a raise, so you move to a nicer apartment. You get a bonus, so you upgrade your car. Before you know it, you are still living paycheck to paycheck, even though you are making more money than ever before. If you want to build real wealth, you have to learn how to break this cycle.
What Does Lifestyle Creep Actually Look Like?
Lifestyle creep is rarely about one giant, irresponsible purchase. It is almost always about the small, invisible decisions you make every single month. It happens because we tend to adjust our baseline for what a “normal” life costs.
Think about your own financial history. When you were a student or just starting your first job, you probably found ways to survive on a very tight budget. Maybe you cooked at home, shared an apartment with roommates, and skipped the fancy subscription services. As you earned more, those restrictions felt like they should disappear. You started eating out more, paying for convenience, and buying nicer clothes.
None of these things are bad on their own. The problem starts when your spending rises in perfect lockstep with your salary. If you earn ten percent more this year and spend ten percent more, your ability to save stays exactly the same. You are essentially working harder for the same financial outcome.
Why Our Brains Trick Us Into Spending More
Human psychology plays a big part in why we overspend. There is a concept called hedonic adaptation. It means we get used to our new level of comfort very quickly. When you first upgrade your internet speed or buy a more expensive phone, it feels like a big luxury. After two weeks, it just feels like the standard. You stop feeling any extra joy from that expense, but the monthly cost stays on your bank statement forever.
Because we adjust so fast, we often feel like we “deserve” to spend more. We look at our bank balance and see that we have more cash, so we assume we can handle higher costs. We often fail to realize that this extra cash is the most powerful tool we have for improving your financial life through saving and investing.
The Math Behind Your Future Savings
Let’s look at a simple example. Imagine you get a raise of $500 per month after taxes. If you decide to put all of that extra money into an investment account that earns a modest return over ten years, that money could grow significantly. Instead of just disappearing into a slightly higher grocery bill or a new streaming subscription, that $500 becomes a base for your future security.
If you don’t save it, that $500 is gone the moment you pay for your upgraded lifestyle. You will never see it again. If you invest it, that money starts working for you. Using our BestPicky Finance Tools, you can see exactly how small monthly choices change your long-term outcome. The difference between spending that raise and saving it is often the difference between struggling at age 50 and having complete peace of mind.
How to Keep Your Spending in Check
You do not have to live like a monk to avoid lifestyle creep. The goal is to be intentional with your money. Here are a few ways to keep your costs under control while your income grows:
- Automate your savings first: Treat your savings like a bill that must be paid. Move that money to a separate account the same day your paycheck hits. If it is not in your main account, you are less likely to spend it.
- Wait 48 hours before big buys: If you see something expensive that you want, force yourself to wait two days. Most of the time, the urge to buy that item will fade, and you will realize you did not actually need it.
- Avoid the “upgraded” cycle: When you get a raise, try to keep your living expenses at your old level for at least six months. This forces you to save the difference without feeling like you are depriving yourself of anything.
- Review your subscriptions: We often sign up for things and forget they exist. Check your bank statement once a month to find services you no longer use.
- Focus on value, not status: Ask yourself if a purchase is actually making your life better or if you are just buying it because you think you should at your current income level.
The Power of the 50/50 Rule
If the idea of not spending any of your raise feels too hard, try the 50/50 rule. Whenever your income goes up, take half of that extra money and put it toward your savings or debt. Use the other half to treat yourself or upgrade your life. This way, you still see the benefits of your hard work, but you are also making sure your future self is protected.
This approach keeps you balanced. It prevents you from feeling punished for your success, but it also stops you from blowing all your progress. It is a simple way to create a habit that lasts for your entire career.
Checking Your Progress
You do not need to obsess over every penny. However, you should check your spending trends every three to six months. Are your costs rising faster than your income? If the answer is yes, you are likely in the middle of lifestyle creep.
Remember that your goal is to buy freedom, not just things. Every dollar you spend on a status upgrade is a dollar that could have been used to reduce your work hours, take an early retirement, or handle an emergency. When you look at your purchases as trade-offs rather than just prices, you start making better decisions naturally.
Lifestyle creep is a silent thief. It steals your potential wealth by turning your hard-earned money into minor comforts that you barely notice after a month. By staying mindful of where your money goes, you keep control over your future. Decide today that your lifestyle will grow slower than your bank account, and you will see the impact for years to come.
Want to Calculate Your SIP?
Click the button above and check your expected SIP returns instantly.