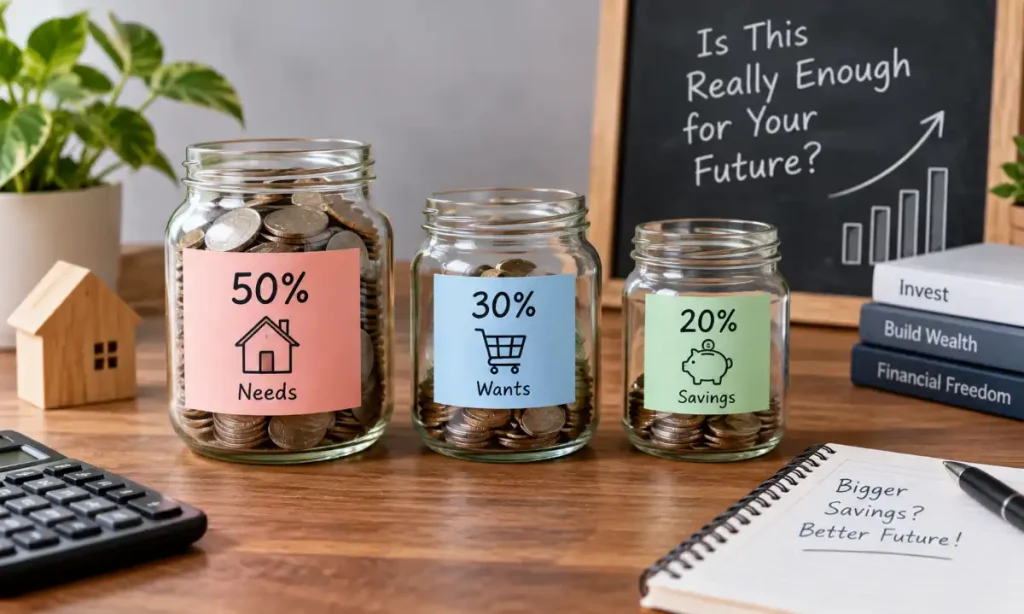
Most of us have heard the common advice for managing money. You take your paycheck, you split it into three buckets, and you call it a budget. Specifically, you put 50 percent toward needs, 30 percent toward wants, and 20 percent toward savings or debt. It sounds simple. It sounds organized. But for many people in 2026, this math is starting to feel like a relic from a different era.
Following a strict percentage-based budget can actually make you feel guilty when life gets expensive. If you are living in a city where rent takes up more than half of your income, trying to hit that 50 percent mark for needs is just not realistic. Let’s look at why this classic rule might be failing you and how you can fix your approach to money.
Why the Math Often Breaks Down
The 50/30/20 rule assumes that your “needs”, things like rent, groceries, and utilities, stay below half of your take-home pay. A few years ago, that might have been a standard target. Today, the cost of living has shifted significantly. For many young professionals or families, housing costs alone can eat up 40 or 50 percent of a monthly budget before you even turn on the lights or buy a carton of milk.
When your needs take up 60 or 70 percent of your pay, the math of the traditional rule forces you to slash your “wants” to zero or raid your “savings” bucket. Neither of these options is great for long-term happiness or financial health. You cannot live a life where every single cent goes to survival, and you definitely cannot afford to stop saving for the future.
The Trap of Fixed Percentages
Budgeting rules are meant to be tools, not laws. The danger of a rigid system is that it ignores the reality of your specific situation. If you earn a lower income, a 50 percent limit for needs is almost impossible to hit in most urban areas. If you earn a high income, saving only 20 percent might mean you are missing out on serious wealth-building opportunities.
When you rely too heavily on a formula, you stop looking at your actual spending habits. You might stop caring about a recurring subscription because you think you are “allowed” to spend that 30 percent on wants. You might stop looking for ways to lower your grocery bill because you feel like you are within your “needs” limit. It creates a false sense of security.
What to Do Instead: The Dynamic Budget
If you want to manage money like a pro, you should focus on your actual expenses rather than arbitrary percentages. Start by tracking exactly where your money went over the last three months. Use your bank statements to see what you really spend on food, transport, and fun.
Once you see the real numbers, try these steps to build a system that works for your life:
- Prioritize your “gap” goal. Instead of forcing your needs into 50 percent, look at the total amount you need to save each month for your goals, like an emergency fund or a house down payment. Subtract that from your income first.
- Control your fixed costs. Look at your rent, insurance, and bills. These are the hardest to change, but they are the biggest drain on your budget. If you cannot change them now, look for small ways to trim the edges, like switching internet providers or canceling unused memberships.
- Assign a “guilt-free” spending limit. Once your savings are set and your mandatory bills are paid, the rest is your discretionary money. This is the amount you can spend on coffee, hobbies, or nights out without checking your phone to see if you are breaking a rule.
If you need help visualizing these numbers, you can visit our BestPicky Finance Tools , EMI, Loan & Investment Calculators to see how small changes in your monthly savings can impact your long-term wealth.
When Percentages Actually Help
To be fair, the 50/30/20 rule is not useless. It is a fantastic starting point for someone who has never tracked their spending before. If you have absolutely no idea where your money goes, using this rule for two months can act as a wake-up call. It highlights if you are wildly overspending on things that do not matter to you.
The goal is to eventually move past the “beginner” rules. Once you have a handle on your cash flow, you should move toward a zero-based approach. This means every dollar has a job, whether that job is paying the electric bill, buying groceries, or building your future.
Stop Chasing the Rule, Start Chasing the Goal
Money management is personal. Someone living in a small town with low rent has a completely different financial reality than someone working in a major city. When you stop trying to fit your life into a neat, percentage-based box, you actually gain more control.
If you need to spend 60 percent on needs right now to stay housed and healthy, do not panic. Accept that as your current reality and look for ways to grow your income or lower your lifestyle costs over time. The “right” budget is the one that allows you to pay your bills, sleep at night, and hit your savings goals without feeling like you are living in a prison.
Also, keep your digital life secure while you track these numbers. If you lose access to your accounts, you cannot budget at all, so learning how to find Gmail password in mobile without phone number is a smart bit of security preparation for your financial records.
Common Questions About Budgeting
Is it okay if I save less than 20 percent?
It is okay to start where you are, but you should always aim to increase your savings rate over time. Even saving one or two percent is better than nothing, provided you are working toward a plan to save more as your income grows.
What if my fixed expenses are over 80 percent of my income?
If your mandatory expenses are that high, your budget is not the problem, your income or your location is. You should look for ways to increase your earnings or consider if a change in living arrangements is possible. You are in a high-risk situation that needs immediate attention.
Should I include debt payments in “needs” or “savings”?
Minimum debt payments are “needs” because they are mandatory. However, any extra money you throw at debt to pay it off faster should be counted toward your “savings” or “wealth-building” bucket. You are essentially “saving” money by avoiding future interest charges.
The bottom line is simple: stop worrying about whether you fit a specific percentage. Focus on the total dollars you are saving and the total dollars you are spending on things that do not bring you value. That is the only math that matters.
Want to Calculate Your SIP?
Click the button above and check your expected SIP returns instantly.